NRI Infrastructure Investing: The Transportation Multiple Playbook (2026)

The Direct Answer
For Non-Resident Indians (NRIs), investing in Indian real estate in 2026 requires abandoning old strategies focused on low-yield urban apartments. The new wealth-generation playbook is centered on Transportation Multiples—buying land near mega-infrastructure projects like the Delhi-Mumbai Industrial Corridor (DMIC) and upcoming greenfield airports just as they transition into the operational phase. Coupled with a strong Rupee arbitrage and a nuanced understanding of the new 12.5% unindexed capital gains tax, 2026 presents a massive, yet complex, geo-arbitrage opportunity.
Tax rates, sections, forms and FEMA limits checked on 2 November 2026 against the Income-tax Act, 2025 and RBI's remittance directions. Bank and processing times are estimates. General information, not tax advice: confirm your case with a CA.
Why 2026 is a Pivotal Year for NRIs
The landscape of Indian real estate has fundamentally shifted. For decades, NRIs parked money in tier-1 city apartments, hoping for steady appreciation and rental yields. Today, urban rental yields in India remain sluggish (often 2-3%), while property prices have plateaued in many saturated micro-markets.
However, India is currently undergoing the largest infrastructure rollout in its history. This is where the smart NRI money is moving in 2026.
1. The Power of the "Transportation Multiple"
A transportation multiple occurs when a major piece of infrastructure—an expressway, a metro line, or an international airport—goes from planned to operational. The land values in the surrounding transition zones experience an exponential, non-linear jump.
If you buy during the "pre-discovery" phase (when construction is underway but operations haven't begun), you capture the steepest part of the appreciation curve.
Key 2026 Example: Dholera SIR Investment
Dholera is India's first greenfield smart city. Its expressway to Ahmedabad opened on 31 March 2026, but the international airport is still under construction (about 80% complete at the July 2026 review, opening target slipped to the end of 2026), so the land here is early-stage, not proven. For NRIs, Dholera is a ground-level entry into the DMIC — after checking the FEMA bar on agricultural land and the plot's TP-scheme stage.
2. The Rupee Depreciation Arbitrage
For NRIs earning in USD, GBP, or AED, the steady depreciation of the Indian Rupee acts as an unearned discount on property prices. A property that cost ₹1 Crore five years ago required significantly more dollars to purchase than a ₹1 Crore property requires today.
While depreciation hurts when repatriating funds, purchasing land in high-growth corridors (aiming for 20-25% IRRs) dramatically outpaces any currency devaluation.
The ROI Calculation
Don't guess your returns. Use our interactive NRI FIRE Accelerator tool to see how allocating a portion of your portfolio to Indian high-growth land can shave years off your retirement timeline compared to standard 8% index funds.
Navigating the New Tax Reality: The 12.5% Capital Gains Rule
The biggest shock to NRI investors recently has been the overhaul of the capital gains tax system.
For property sales executed on or after July 23, 2024 (and fully active for 2026 transactions):
- The Long-Term Capital Gains (LTCG) rate has been reduced to a flat 12.5%.
- However, the indexation benefit has been removed completely for NRIs.
The TDS Trap
When an NRI sells a property, the buyer is required to deduct Tax Deducted at Source (TDS). For long-term assets (held more than 24 months) the rate is 13% to 14.95% (12.5% plus surcharge and cess). Unless the Assessing Officer issues a certificate, buyers generally deduct on the whole amount paid, because their route to anything less is an application to the Assessing Officer. This means a significant chunk of your cash flow is locked up by the Income Tax Department until you file your returns.
How to fight back: You should apply early enough to have a Lower Deduction Certificate (Form 128, old Form 13) before the buyer's first payment, including any advance at agreement.
Want to run the math on your specific property?
Use our interactive NRI Capital Gains & TDS Estimator to see exactly how much tax you owe and how much money will be blocked in TDS.
FEMA Rules: What NRIs Can and Cannot Buy
The Foreign Exchange Management Act (FEMA) strictly regulates NRI investments.
What You CAN Buy:
- Residential property (apartments, villas, residential plots)
- Commercial property (offices, retail spaces, industrial plots)
What You CANNOT Buy:
- Agricultural land
- Plantation property
- Farmhouses
Note: If you inherit agricultural land, you can hold it, but you cannot purchase more. If you plan to buy land for investment, you must ensure it has clear Non-Agricultural (NA) conversion and is part of approved Town Planning (TP) schemes.
The Core 2026 NRI Strategy
If you are an NRI looking to deploy capital into India in 2026, here is the blueprint:
- Avoid Saturated Markets: Ignore standard 3BHK apartments in Gurgaon, Mumbai, or Bangalore if your goal is aggressive wealth generation. The yields don't justify the cross-border hassle.
- Follow the Infrastructure: Identify nodes along the Delhi-Mumbai Industrial Corridor (DMIC) or upcoming tier-2 logistics hubs where government spending is massive.
- Focus on Clean Paperwork: Only buy RERA-approved, NA-cleared plots within official Smart City boundaries (like the Dholera SIR Activation Area).
- Plan Your Exit Tax Now: Before purchasing, consult a CA to understand how you will utilize Sections 82, 85, or 86 of the Income-tax Act, 2025 (old Sections 54, 54EC and 54F) to shield your future gains from the 12.5% unindexed tax rate.
Frequently Asked Questions
Can an NRI get a home loan in India?
Yes, the Reserve Bank of India (RBI) permits NRIs to secure home loans from Indian financial institutions for purchasing residential properties. The loan amount usually ranges from 75% to 80% of the property value, and repayment must be made via inward remittances through NRE or NRO accounts.
How much money can an NRI repatriate after selling a property?
NRIs can repatriate a maximum of USD 1 Million per financial year from their NRO account, covering NRO balances, sale proceeds and inherited assets; above that needs RBI approval. Property bought in foreign exchange or from NRE/FCNR(B) funds has a separate route for not more than two residential properties, so ask your bank how it applies to you. Your bank will ask for the tax paperwork it needs. For sale proceeds that is usually Form 145 (old Form 15CA), plus a CA's Form 146 (old Form 15CB) or an Assessing Officer certificate where the remittance is chargeable to tax and above ₹5 lakh in the tax year. Your CA and bank will decide which Part fits.
Is Joint Ownership allowed for NRIs?
Yes, NRIs can purchase property jointly with another NRI or a Resident Indian. However, the payment should be proportional to ownership, or cleanly documented as a loan or gift, to verify the money trail for tax purposes.
What is the difference between an NRE and NRO account for property?
An NRE (Non-Resident External) account is used to transfer foreign earnings to India, and funds here are fully repatriable and tax-free in India. An NRO (Non-Resident Ordinary) account is used to manage income earned within India (like rent or property sale proceeds). NRO funds face taxation and repatriation limits: current income can go out after tax, and NRO balances, sale proceeds and inherited assets up to USD 1M per financial year.
Read Next
Beyond the Beach: Why the Mopa 'Aerocity' Zone is the Real 10x Opportunity of 2026
Most investors are still chasing overcrowded vacation rentals in Assagao. Smart money is moving north to Pernem's commercial zone. Here's the data behind the Mopa Arbitrage.
5 Common Real Estate Scams Targeting NRIs (And How to Avoid Them)
From 'Double Selling' to 'GPA Fraud'. We break down the most common traps set for remote investors and how to safeguard your capital.
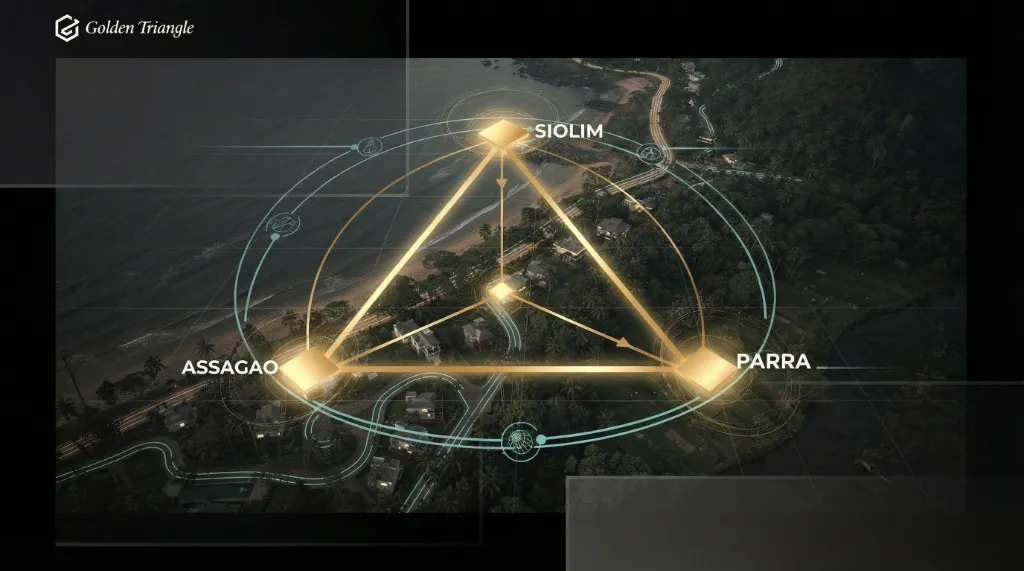
The "Golden Triangle" Report 2026: Assagao, Siolim, & Parra Price Analysis
Why Assagao is hitting ₹45,000/sqft while Parra offers a value entry. We decode the pricing and ROI of North Goa's most expensive corridor.